What is a general ledger?
Quick answer
The general ledger, or GL, is the master record of a business's accounting: one running page for each account in the chart of accounts, holding every transaction posted to it. Financial statements such as the profit and loss and the balance sheet are built directly from it.
Last updated
Updated · By Robert Breen
Why it matters for a small business
Think of the ledger as the place where everything ends up. Bills, sales, payroll, bank fees and loan payments are first recorded in smaller records, then posted to the ledger account they belong to. When you ask why office supplies cost more this quarter, you open that account and read the transactions behind the number.
Because every report comes from the ledger, errors in it spread everywhere. A purchase coded to the wrong account distorts two statements at once. That is why bookkeepers reconcile and review before closing a period: the ledger should reflect reality before anyone trusts a report built on it.
In a real lesson: Build an AI Agent That Categorizes Business Expenses
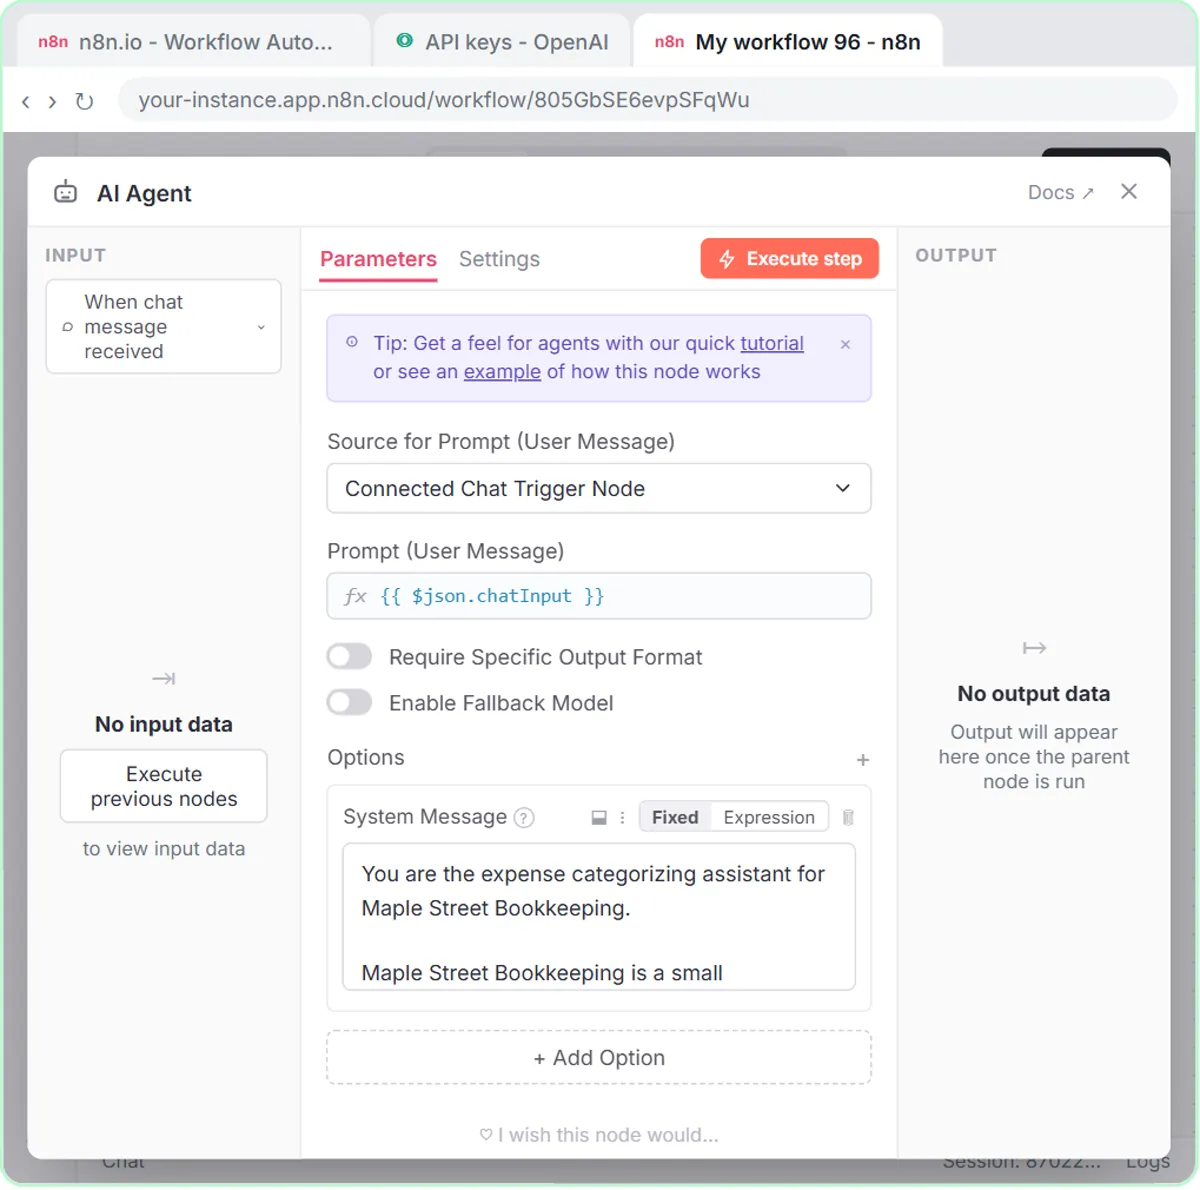
In the AI Expense Categorizer Agent lesson, you build an agent for Maple Street Bookkeeping, a made-up firm. It sorts each expense into one of six categories: Office Supplies, Software & Subscriptions, Meals, Travel, Utilities or Needs Review. It also writes a one-sentence note and saves rows to a Google Sheet called Expense Log, with Date, Vendor, Amount, Category and Note.
In the test, three expenses go in: Corner Office Supply for printer paper and toner, CloudLedger for monthly accounting software, and Harbor Street Cafe for a client lunch. Each gets a category and a note.
This is not a general ledger, and the lesson does not claim it is. It is a categorized list that a bookkeeper reviews before anything is posted, as the system prompt says. The categories do resemble ledger accounts, so the sheet shows what an entry's destination looks like. Real posting happens in accounting software.
Try this lesson free or read the step-by-step guide.
Common confusions
General ledger vs chart of accounts
The chart of accounts is the list of account names and numbers. The ledger is the activity inside those accounts. One is the filing cabinet labels, the other is the papers inside.
General ledger vs bank statement
The bank statement is the bank's record of your cash. The ledger is your own record of everything. Bank reconciliation is the check that the two agree on cash.
Tips
- Click into any account on a report to see the transactions behind it. It is the fastest way to find a miscoded item.
- Keep your chart of accounts short and consistent so the ledger stays readable.
- Review the ledger monthly. Small errors are far easier to find within a few weeks than at year end.
Related terms
More Business terms
Where you use it: free lessons
- Build an AI Agent That Categorizes Business Expenses (n8n, 12 min)
- Turn a Client Meeting into Action Items and a Follow-Up Email (Accounting Firms) (ChatGPT, 9 min)
- An AI Resume Screener, with a Fairness Step (Recruiting & HR) (n8n, 14 min)
Frequently asked questions
- Is a spreadsheet a general ledger?
- A well-kept spreadsheet can act as one for a very small business, but it lacks the built-in checks that accounting software provides, such as balanced entries and locked periods.
- Who is responsible for the ledger?
- Usually a bookkeeper or accountant maintains it, and the owner reviews the reports. Responsibility for accuracy still sits with the business.