What is a fixed asset?
Updated · By Robert Breen
A fixed asset is a long-lasting item a business buys to use in its work for more than a year, such as a truck, machinery, computers or a building. Instead of recording the whole cost as an expense when you buy it, the books record it as an asset and spread its cost over time through depreciation.
Why it matters for a small business
How a big purchase is recorded changes your numbers. Put a $38,000 truck in as an expense and that month looks like a huge loss. Record it as an asset and your profit and loss reflects the cost gradually over the years you use it. If you financed it, the loan is recorded separately as a liability.
This is also where tax rules and accounting choices meet. How and when an asset is depreciated can affect your taxes, and the rules are detailed and change. This page is general information, not tax or accounting advice. Have a CPA or enrolled agent decide how a specific purchase should be recorded and depreciated.
In a real lesson: Turn a Client Meeting into Action Items and a Follow-Up Email (Accounting Firms)
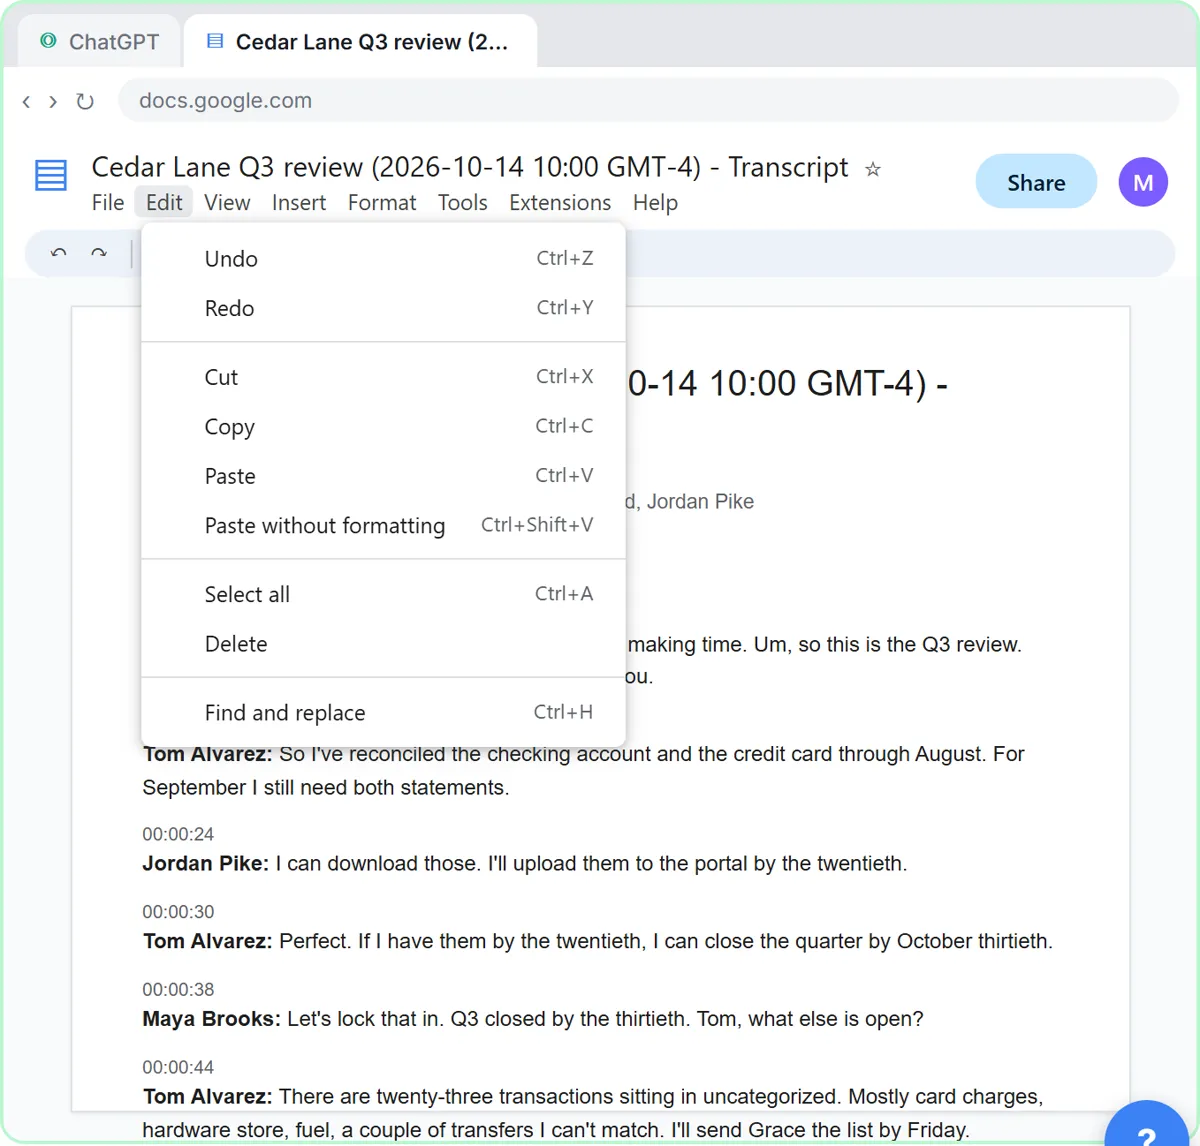
In the Summarize a Client Meeting lesson, Grace Whitfield of Cedar Lane Landscaping, a made-up client, mentions a new truck: bought August twelfth, thirty-eight thousand, mostly financed through the bank. Maya Brooks of Millbrook Accounting, also made up, decides how it goes in the books: "we'll set it up as equipment with a loan against it, not as an expense."
She also asks the client for the purchase agreement and loan paperwork, and parks one question on purpose: "how we depreciate it, let's leave that for the year-end planning meeting. That's a bigger conversation."
When you ask ChatGPT for the decisions and open questions, the truck shows up in both places: recording it as equipment is a decision, and depreciation is an open question. ChatGPT doesn't try to answer it, because the request said to use only what's in the transcript. That is the right behavior for a question that belongs to the accountant.
Try this lesson free or read the step-by-step guide.
Common confusions
Fixed asset vs expense
An expense, like fuel or office supplies, is used up quickly and recorded when it happens. A fixed asset is used for years and its cost is spread out. Where the line falls is set by accounting rules and your accountant's policy.
Asset vs the loan that paid for it
The truck is an asset; the bank loan is a liability. They are recorded separately, and loan payments are not the same as the truck's expense.
Tips
- Tell your bookkeeper about big purchases when they happen, with the paperwork.
- Keep purchase agreements and loan documents in one place for each asset.
- Let AI list questions for your accountant, not decide how to depreciate something.
Related terms
Where you use it: free lessons
Frequently asked questions
- Is every piece of equipment a fixed asset?
- Not always. Smaller purchases are often expensed under a threshold your accountant sets. Ask them where your business draws the line.
- What is depreciation?
- It is spreading the cost of a fixed asset over the years you use it. The method and timing can affect taxes, so it is a decision for your CPA or enrolled agent.